What renters insurance actually covers
Renters insurance is built around three main protections: personal property coverage, liability coverage, and loss of use coverage.
Personal property coverage pays to repair or replace your belongings if they are stolen, damaged by fire, or destroyed by certain other events listed in your policy. This includes furniture, clothing, electronics, and similar items. The coverage typically applies whether the loss happens inside your apartment or elsewhere, so a stolen laptop from your car may be covered too, depending on your policy terms.
Liability coverage protects you financially if someone is injured in your apartment or if you accidentally damage someone else's property. For example, if a guest slips and sues you, liability coverage can help pay legal costs and any settlement up to your policy limit.
Loss of use coverage (sometimes called additional living expenses) pays for a hotel or temporary housing if your unit becomes uninhabitable after a covered event like a fire. It can also cover meals and other costs above your normal living expenses while repairs are made.
When you move into a new apartment, photograph every room before you unpack. These images establish a baseline record of your belongings and the unit's condition.
Visual documentation can resolve disputes with landlords and speed up insurance claims, particularly after a theft or fire.
If you own high-value items like an engagement ring, a camera kit, or a musical instrument, ask your insurer about a scheduled endorsement to cover those items at their full appraised value.
Standard personal property limits often cap payouts on jewelry and electronics well below replacement cost, leaving a significant gap.
What renters insurance does not cover
Flooding from outside your unit is generally not covered by a standard renters insurance policy. Separate flood insurance is available through the National Flood Insurance Program (NFIP) and some private carriers. If you live in a flood-prone area, this gap matters.
Earthquakes are also typically excluded. Separate earthquake coverage is available as an add-on or standalone policy in states where seismic risk is significant.
Your roommate's belongings are usually not covered unless they are specifically listed on the policy. Standard policies cover the named insured's property, so each roommate generally needs their own policy.
Damage you intentionally cause is excluded. High-value items such as jewelry, fine art, or musical instruments may have per-item payout limits under a standard policy; a scheduled personal property endorsement (an add-on that lists specific high-value items) can close that gap.
Flood and earthquake coverage gaps
Standard renters insurance policies do not cover flood damage or earthquake damage. If you rent in an area with either risk, a separate policy or endorsement is needed. Review FEMA flood maps and state seismic hazard resources to assess your exposure before assuming you are covered.
How much renters insurance costs
According to the National Association of Insurance Commissioners (NAIC), the average annual premium for renters insurance in the United States has historically been around $150 to $200 per year, though costs vary by location, coverage amount, and deductible choice. That works out to roughly $12 to $17 per month.
Several factors affect your premium. Your ZIP code matters because local crime rates and weather risks influence pricing. The coverage amount you select, your chosen deductible, and whether you bundle renters insurance with an auto policy (a discount many insurers offer) all shift the final cost.
$150-$200
Average annual renters insurance premium (U.S.)
According to historical data from the National Association of Insurance Commissioners (NAIC).
55%
Share of renters without renters insurance
An Insurance Information Institute survey found roughly half of renters do not carry renters insurance.
A higher deductible lowers your premium but increases what you pay out of pocket before insurance kicks in. A lower deductible does the opposite. Most renters choose a deductible between $250 and $1,000.
How to figure out how much coverage you need
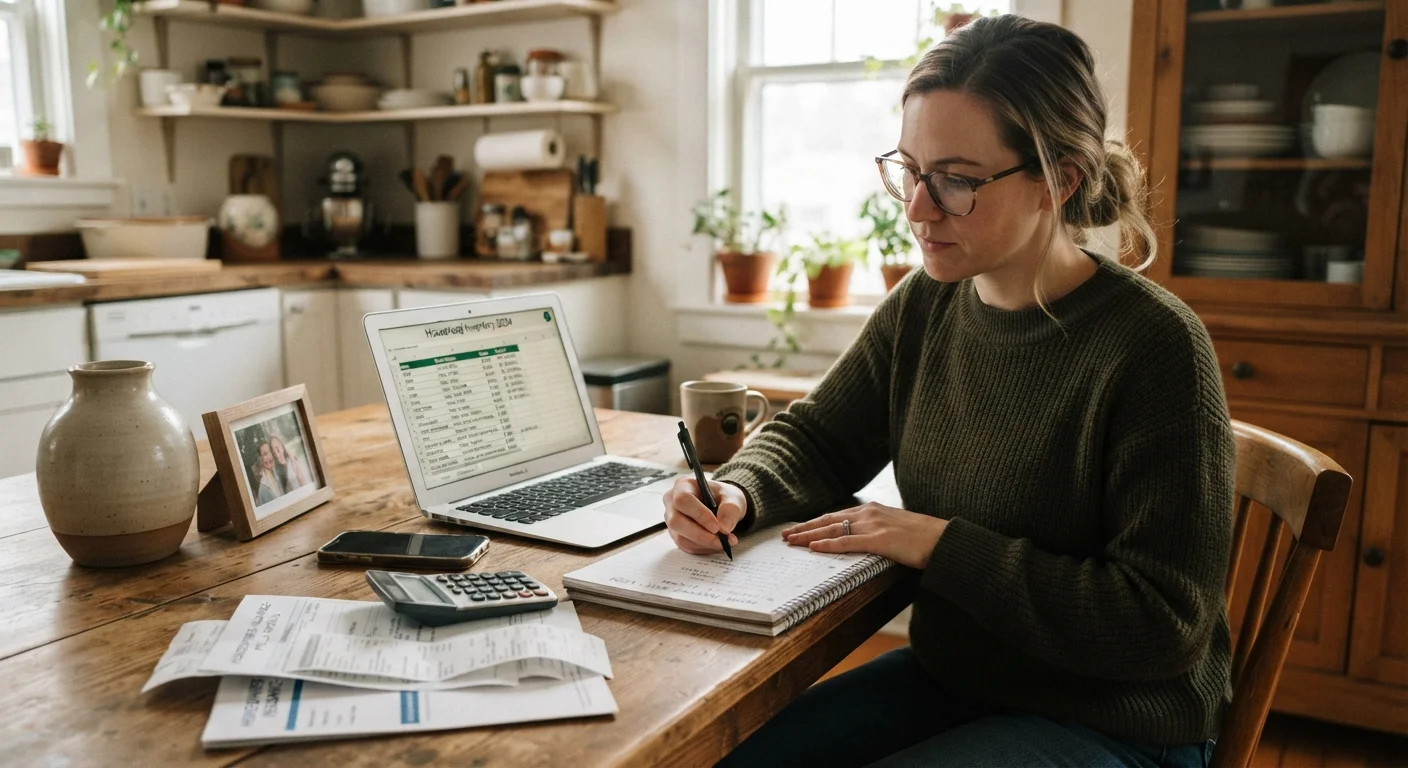
The right coverage amount starts with knowing what you own. A home inventory is a list of your possessions with estimated values. You can create one using a spreadsheet or a dedicated app. Walk through every room and record items, approximate purchase prices, and serial numbers where applicable.
Once you have a total, you face a choice between two payout methods. Actual cash value (ACV) policies pay what your belongings were worth at the time of loss, factoring in depreciation. A five-year-old couch will pay out far less than what a new one costs. Replacement cost value (RCV) policies pay what it costs to replace the item with a new equivalent, regardless of age. RCV policies typically cost more in premiums but close the gap depreciation creates.
For liability, most policies start at $100,000. If you have savings or assets that could be at risk in a lawsuit, a higher limit may be appropriate. A licensed insurance agent can help you think through the right amount for your situation.
How to evaluate a policy before you buy
Read the declarations page carefully. It summarizes your coverage limits, deductible, premium, and named perils (the specific events your policy covers). Some policies are "open perils" or "all-risk," meaning they cover everything except what is explicitly excluded. Others are "named perils" policies, which only cover events listed in the document. Named perils policies are generally narrower.
Check the insurer's financial strength rating through a rating agency such as AM Best before committing. A financially stable insurer is more likely to pay claims reliably.
Ask about the claims process before you sign. How do you file? What documentation is required? What are typical processing times? A policy is only as useful as its claims experience.
If your landlord requires you to carry renters insurance as a lease condition, confirm that their minimum coverage requirements are met by any policy you consider. Keep a copy of your declarations page accessible in case you need to provide proof of insurance.
This article is for general informational purposes only and does not constitute insurance, legal, or financial advice. Coverage terms, exclusions, and pricing vary by insurer and state. Consult a licensed insurance professional for guidance specific to your situation.